Online checkout has become one of the most important points in the customer journey, but it is also a major target for fraud. As digital commerce expands, merchants face increasingly sophisticated attempts involving stolen cards, account takeovers, automated bots, fake identities, and suspicious purchasing patterns. A strong fraud prevention strategy therefore needs to do more than simply reject transactions that appear unusual. It should identify genuine risk while allowing legitimate customers to complete purchases smoothly.
stripe provides merchants with tools and transaction signals that can support a layered approach to payment security. When these capabilities are combined with sensible checkout policies, customer verification, monitoring, and internal controls, businesses can create a more resilient payment process. The goal is not to eliminate every potentially risky transaction, because overly aggressive fraud controls can also block valuable customers. Instead, merchants should focus on distinguishing legitimate behavior from meaningful warning signs.
Understanding How Checkout Fraud Happens
Checkout fraud can take several forms, and understanding the differences helps merchants build better defenses. One common example is card-not-present fraud, where criminals use stolen card information to purchase products without physically presenting the card. Fraudsters may also test small transactions before attempting larger purchases, making transaction patterns especially important.
Another growing problem is account takeover. In this scenario, attackers gain access to an existing customer account and use stored payment information, loyalty balances, or saved addresses to place unauthorized orders. Promotional abuse can create additional losses when criminals exploit discount codes, referral programs, refunds, or free-trial offers.
Common checkout fraud warning signs include:
- Multiple transactions from unusual locations
- Rapid purchases using different payment methods
- Repeated declined payment attempts
- Billing and shipping information that do not match
- Unusually large orders from new customers
- Several accounts using the same suspicious details
- Sudden changes to account information before payment
No single signal proves that a customer is fraudulent. Effective detection comes from evaluating multiple indicators together.
Why Fraud Detection Requires a Layered Strategy
A single fraud rule rarely provides enough protection for a growing online store. Criminal behavior changes quickly, while legitimate purchasing behavior can vary significantly between customers. For example, a high-value order may be perfectly normal for a business buyer but unusual for someone making a first purchase from a consumer-focused store.
A layered fraud strategy combines automated analysis with merchant-defined controls. stripe can contribute transaction-level intelligence that helps merchants evaluate payment risk, while businesses can establish additional rules based on their products, customers, regions, and order values.
A practical layered model may include:
- Automated risk assessment to identify suspicious transactions.
- Transaction rules for unusual amounts, locations, or frequencies.
- Customer verification when additional confirmation is appropriate.
- Manual review for transactions falling into an uncertain risk category.
- Post-payment monitoring to identify emerging patterns.
- Chargeback analysis to improve future fraud controls.
This approach creates several defensive layers instead of depending on one automated decision.
Using Transaction Signals to Identify Suspicious Activity
Transaction signals are valuable because fraud often produces patterns that are difficult to notice manually. A merchant might see hundreds of orders in a day, making it impractical to inspect every transaction individually. Automated systems can help identify combinations of signals that deserve attention.


For example, consider a new customer placing an unusually expensive order, using a billing address in one country, shipping to another, and attempting several payments within a short period. None of these details automatically means fraud. Together, however, they may justify additional scrutiny.
Merchants should pay attention to factors such as:
- Transaction amount and frequency
- Payment attempt history
- Customer account age
- Billing and shipping consistency
- Device and behavioral patterns
- Geographic anomalies
- Previous successful or unsuccessful transactions
The important principle is context. A signal becomes more useful when considered alongside other information rather than treated as an automatic reason for rejection.
Building Smarter Rules for High-Risk Transactions
Merchant-defined rules can strengthen automated fraud detection by addressing risks specific to a particular business. A luxury retailer, for instance, may have different fraud concerns than a subscription-based software company. Similarly, a digital goods merchant may need stronger controls around instant fulfillment because fraudulent purchases can be difficult to recover once access has been granted.
With stripe, merchants can structure their payment workflows around risk signals and business requirements. Rules should be specific enough to catch meaningful anomalies without creating unnecessary friction for ordinary customers.
Useful rule categories can include:
- High-value first-time purchases
- Repeated payment failures
- Unusual purchase frequency
- Orders from restricted regions
- Mismatched customer information
- Sudden changes in purchasing behavior
- Multiple accounts sharing unusual characteristics
Rules should also be reviewed regularly. A rule that worked effectively six months ago may become less useful as customer behavior, product offerings, and fraud techniques change.
Balancing Fraud Prevention with Customer Experience
Fraud prevention becomes counterproductive when legitimate customers are constantly challenged or rejected. A shopper who receives unnecessary verification requests may abandon the checkout process and choose another merchant. For this reason, effective fraud prevention should distinguish between high-risk and uncertain transactions.
Instead of treating every unusual transaction as fraudulent, merchants can create different response levels. Low-risk transactions can move through checkout normally. Moderate-risk transactions may receive additional verification. High-risk transactions can be held for review or declined according to the merchant’s policies.
This risk-based approach helps businesses protect revenue while maintaining a convenient customer experience.
A useful framework is:
| Risk Level | Typical Indicators | Suggested Response |
|---|---|---|
| Low | Consistent customer and payment details | Approve normally |
| Moderate | Some unusual activity or inconsistent signals | Request verification |
| High | Multiple strong fraud indicators | Review or decline |
| Critical | Clear evidence of unauthorized activity | Block and investigate |
The exact thresholds should depend on the merchant’s products, customers, and acceptable level of risk.
Strengthening Authentication at Checkout
Authentication can provide an additional layer of protection when transaction risk is elevated. Rather than applying extra verification to every customer, merchants can use risk-based approaches that introduce stronger checks when circumstances justify them.
stripe supports payment workflows that can incorporate authentication mechanisms designed to reduce unauthorized transactions while keeping routine purchases relatively simple. The best implementation depends on factors such as customer location, payment method, transaction value, and applicable payment requirements.
Merchants should consider authentication particularly for transactions involving:
- Expensive products
- New customer accounts
- Unusual purchasing patterns
- Suspicious account changes
- High-risk payment behavior
- Orders that differ significantly from a customer’s normal activity
Authentication should be viewed as one component of a broader security strategy rather than a complete fraud solution.
Monitoring Failed Payments and Repeated Attempts
Declined transactions can reveal important information about fraud attempts. Criminals sometimes test stolen payment credentials through multiple small purchases before attempting a larger transaction. A merchant that examines only successful payments could miss this activity.
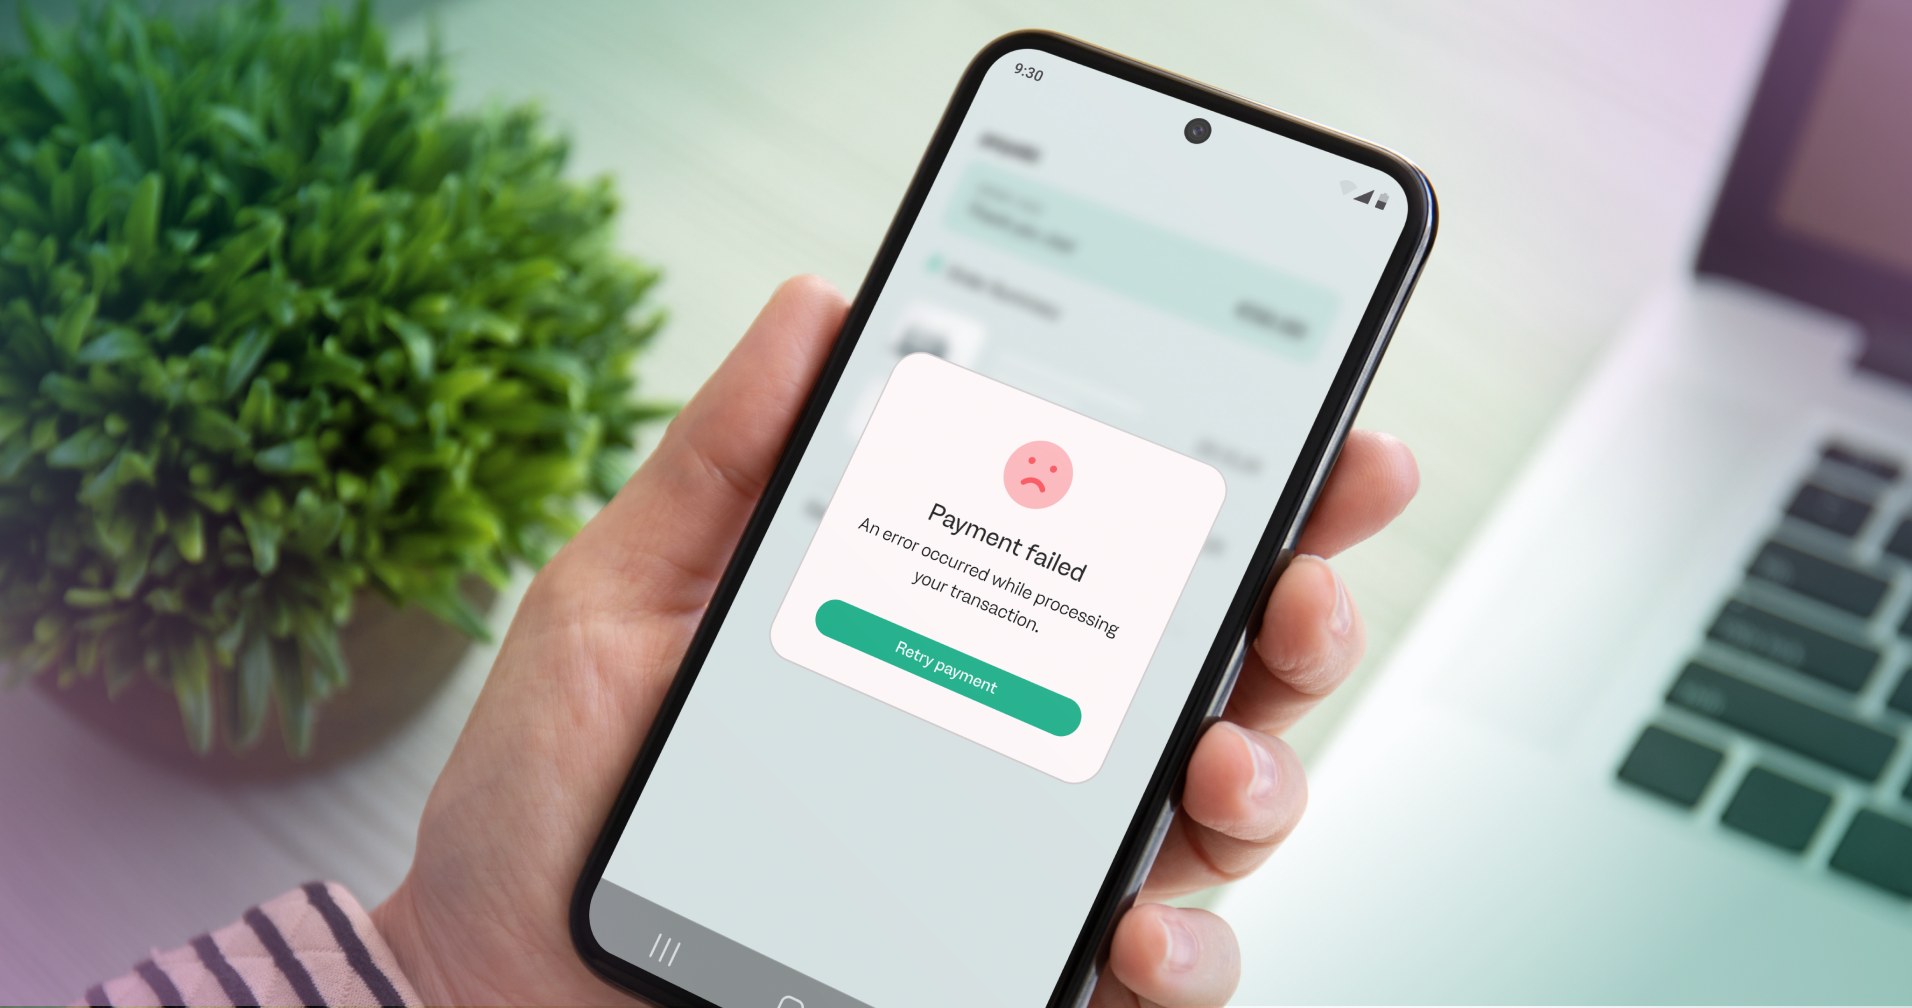
Tracking payment attempts over time can help identify unusual patterns. For example, several failed attempts followed by a successful high-value transaction may deserve closer inspection. Likewise, numerous cards being attempted from the same customer account or device could indicate automated abuse.
Businesses should establish monitoring procedures for:
- Repeated declines within short periods
- Multiple payment methods linked to one account
- Rapid changes in transaction amounts
- Unusual spikes in failed payments
- Repeated attempts involving similar customer details
These signals can also help merchants identify automated attacks and adjust their checkout defenses before losses become significant.
Reducing Fraud Through Account Security
Payment security does not begin at the payment button. Customer accounts can become the entry point for fraud, particularly when shoppers save payment information or maintain valuable loyalty balances.
Merchants should therefore protect account creation, login, password recovery, and profile changes alongside payment processing. Security controls should be designed to detect unusual behavior without unnecessarily frustrating genuine users.
Helpful practices include:
- Encouraging strong, unique passwords
- Monitoring unusual login activity
- Applying additional verification after sensitive account changes
- Limiting suspicious automated requests
- Protecting password-reset workflows
- Reviewing changes to shipping and billing information
If an attacker gains control of an established account, even a well-protected payment page may not prevent every unauthorized purchase. Account security and payment security must work together.
Using Data to Improve Fraud Decisions
Fraud prevention should be treated as an ongoing process rather than a one-time configuration task. Merchants should regularly examine transaction outcomes, chargebacks, refunds, declines, and customer complaints to determine whether their controls are working effectively.
stripe reporting and transaction information can help businesses identify patterns that may otherwise remain hidden. The objective is to discover where fraud occurs, which rules are producing useful results, and where legitimate customers may be experiencing unnecessary friction.
Useful performance indicators include:
- Chargeback rate
- Fraud-related losses
- False-decline rate
- Approval rate
- Manual-review volume
- Verification success rate
- Average order value for disputed transactions
Reviewing these measurements over time makes it easier to fine-tune fraud controls based on actual business performance.
Creating a Practical Fraud Response Process
Detection is only the first step. Merchants also need a clear response process for suspicious transactions. Employees should know what happens when an order is flagged, who reviews it, which information can be checked, and when an order should be canceled or held.
A simple process might involve four stages. First, automated controls identify potentially suspicious activity. Second, the transaction receives an appropriate risk response, such as verification or manual review. Third, the merchant examines available order and customer information. Finally, the business records the outcome and uses the information to improve future controls.
Consistency is important. Without documented procedures, employees may make different decisions when facing similar transactions. A structured process improves both security and operational efficiency.
How Small Merchants Can Start Without Overcomplicating Security
Smaller businesses may not have dedicated fraud teams, but they can still establish meaningful protections. The most effective starting point is usually a combination of basic account security, transaction monitoring, sensible risk rules, and regular review.
stripe can form part of this foundation by giving merchants payment-related capabilities that can be integrated into their broader fraud prevention workflow. Businesses should begin with the risks most relevant to their products rather than attempting to create dozens of complicated rules immediately.
Start by identifying:
- Your most common fraud patterns
- Your highest-risk products
- Typical transaction values
- Regions where you operate
- Common causes of chargebacks
- Checkout steps where customers abandon purchases
Once these areas are understood, merchants can introduce targeted controls and measure their impact.
Future-Proofing Your Checkout Security
Fraud tactics continue to evolve alongside digital commerce. Automated attacks, synthetic identities, account takeovers, and increasingly sophisticated social engineering can make traditional fraud controls less effective over time. Merchants therefore need a strategy that can adapt.
stripe can be part of an adaptive payment security framework when combined with continuous monitoring and thoughtful business rules. Merchants should periodically review their fraud data, update internal policies, assess new payment risks, and train employees to recognize suspicious activity.
The future of checkout security will depend increasingly on contextual risk assessment. Instead of asking whether a single transaction looks suspicious, businesses can evaluate whether the transaction fits the customer’s broader behavior and purchasing history.
Conclusion
Preventing checkout fraud requires more than declining questionable payments. Successful merchants combine automated risk signals, authentication, transaction rules, account protection, monitoring, and human judgment to create multiple layers of defense. The objective is to stop fraudulent activity while allowing legitimate customers to purchase without unnecessary barriers. By using stripe strategically and pairing payment intelligence with business-specific controls, online merchants can build a stronger and more adaptable checkout environment. Regular analysis of chargebacks, failed payments, suspicious patterns, and false declines can further improve decision-making.