
Introduction
In today’s digital economy, businesses need reliable and convenient payment solutions to serve customers, manage transactions, and maintain smooth financial operations. As online shopping, subscription services, digital platforms, and mobile commerce continue to expand, customers expect payment experiences that are quick, secure, and easy to understand. A complicated checkout process can discourage potential buyers, while a convenient payment system can help businesses create a better customer experience. For this reason, choosing the right payment technology has become an important part of modern business planning.
Stripe is a payment technology platform designed to help businesses accept and manage payments through websites, mobile applications, and other digital channels. It provides tools that support online transactions, recurring billing, payment processing, and financial operations. From small businesses launching their first online store to established companies managing large transaction volumes, payment infrastructure can influence how efficiently daily operations run.
The growing importance of digital payments has also changed how businesses approach customer service and financial management. Companies now look beyond simply accepting money; they want systems that can integrate with their existing technology, provide useful transaction information, and support different business models. Understanding the capabilities of modern payment platforms can help business owners make informed decisions and develop a smoother payment experience for their customers.
Understanding the Role of Stripe in Modern Business
Payment processing is an essential part of almost every commercial operation. Whenever a customer purchases a product or service online, several activities take place behind the scenes. The payment information must be collected, securely transmitted, checked, and processed before the transaction can be completed. A dependable payment infrastructure helps coordinate these activities while reducing unnecessary complications for both customers and merchants.
Stripe offers payment infrastructure that allows businesses to accept payments through different digital channels. Its services support various payment methods, including cards and eligible local payment options, depending on the business location and account configuration. Businesses can use its payment tools to create checkout experiences, manage transactions, and connect payment activities with other operational systems. This flexibility makes payment technology relevant to companies operating in retail, software, education, professional services, and subscription-based industries.
Another important consideration is the ability to manage payments as a business grows. A company may initially process only a small number of orders, but its requirements can change when it begins serving customers in new markets or introducing additional products. Payment infrastructure that supports different transaction types and integration options can make expansion easier to manage. However, businesses should always evaluate available features, pricing, supported countries, and eligibility before choosing a particular solution.
How Digital Payment Processing Makes Transactions Easier
Digital payment processing has become an important requirement for businesses that want to provide convenient purchasing experiences. Traditional payment methods often involve manual activities, additional paperwork, and slower transaction management. Digital systems can simplify these processes by allowing customers to complete purchases electronically while businesses receive transaction information through a centralized platform. This approach can save time, improve record management, and reduce the administrative workload associated with everyday sales.
With Stripe, businesses can integrate payment processing into their websites, applications, and online services. For example, an online clothing store can allow customers to select products, enter their payment details, and complete an order without requiring manual payment confirmation. Similarly, a consulting company can collect service fees through a digital checkout process. These capabilities are particularly useful for businesses that handle multiple orders and need a consistent way to monitor incoming payments.
The customer experience is another important advantage of digital payment processing. Buyers generally prefer checkout experiences that are simple, transparent, and compatible with their preferred payment methods. When customers can complete transactions without unnecessary steps, they may feel more confident about purchasing. Businesses can therefore benefit from choosing payment solutions that balance convenience, security, and reliability.
Important Features That Support Business Transactions
Modern payment platforms offer more than basic transaction processing. They provide different tools that help businesses manage customer payments, automate revenue collection, and understand financial activity. These features can be particularly valuable when a company wants to improve its operational efficiency without building every payment-related function independently.
Stripe provides several payment and financial management capabilities that can support different business requirements. The availability of individual services depends on the country, account eligibility, and selected integration.
Online Payment Acceptance
Online payment acceptance allows businesses to collect money through digital channels instead of depending entirely on physical payment methods. Companies can integrate checkout experiences into websites and applications, making it easier for customers to purchase products or services from different locations. Hosted checkout pages and customizable payment components can also help businesses select an implementation that matches their technical requirements.
For example, an online education company may offer paid courses through its website. Customers can choose a course, proceed to checkout, and submit payment electronically. Once the transaction is completed, the business can use its connected systems to manage access to the purchased service. This creates a more organized purchasing journey and reduces the need for manual payment coordination.
Recurring Payments and Subscription Management
Subscription-based businesses depend on regular payments from customers. Software companies, digital learning platforms, membership services, and content providers frequently use recurring billing models to collect revenue at scheduled intervals. Managing these payments manually can become complicated as the customer base increases.
Modern billing tools help businesses create recurring payment schedules, manage subscription plans, and monitor billing activity. They can also support different pricing structures, including monthly subscriptions, annual plans, and usage-based billing. These capabilities make it easier for companies to organize revenue collection while providing customers with a consistent payment arrangement.
A software business, for instance, may offer basic, professional, and premium subscription plans. Customers can select the option that suits their needs, while the company manages billing according to the selected plan. This approach can improve payment organization and help businesses develop predictable revenue models.
Fraud Prevention and Payment Security
Security is one of the most important considerations when handling online transactions. Businesses must protect customer information and reduce the possibility of unauthorized payments. Fraudulent transactions can result in financial losses, customer complaints, and additional administrative work. Therefore, companies should consider security capabilities when evaluating payment infrastructure.
Payment platforms offer tools that can help identify suspicious activity and manage transaction risks. Stripe Radar, for example, uses machine learning to help detect potentially fraudulent payments. Businesses can also apply suitable verification measures and review transaction activity to identify unusual patterns. However, automated fraud detection does not eliminate every risk, so merchants should maintain appropriate security practices and monitor their payment operations.
Payment Management and Reporting
Accurate transaction records are necessary for understanding business performance. Companies need to know how much revenue they generate, which payments have been completed, and whether refunds or disputes require attention. A centralized payment dashboard can make these activities easier to monitor.
Reporting tools help businesses review transaction information and organize financial records. Depending on the available features and integrations, companies can connect payment information with accounting software, customer management systems, and internal reporting tools. This can reduce repetitive data entry and support more informed business decisions.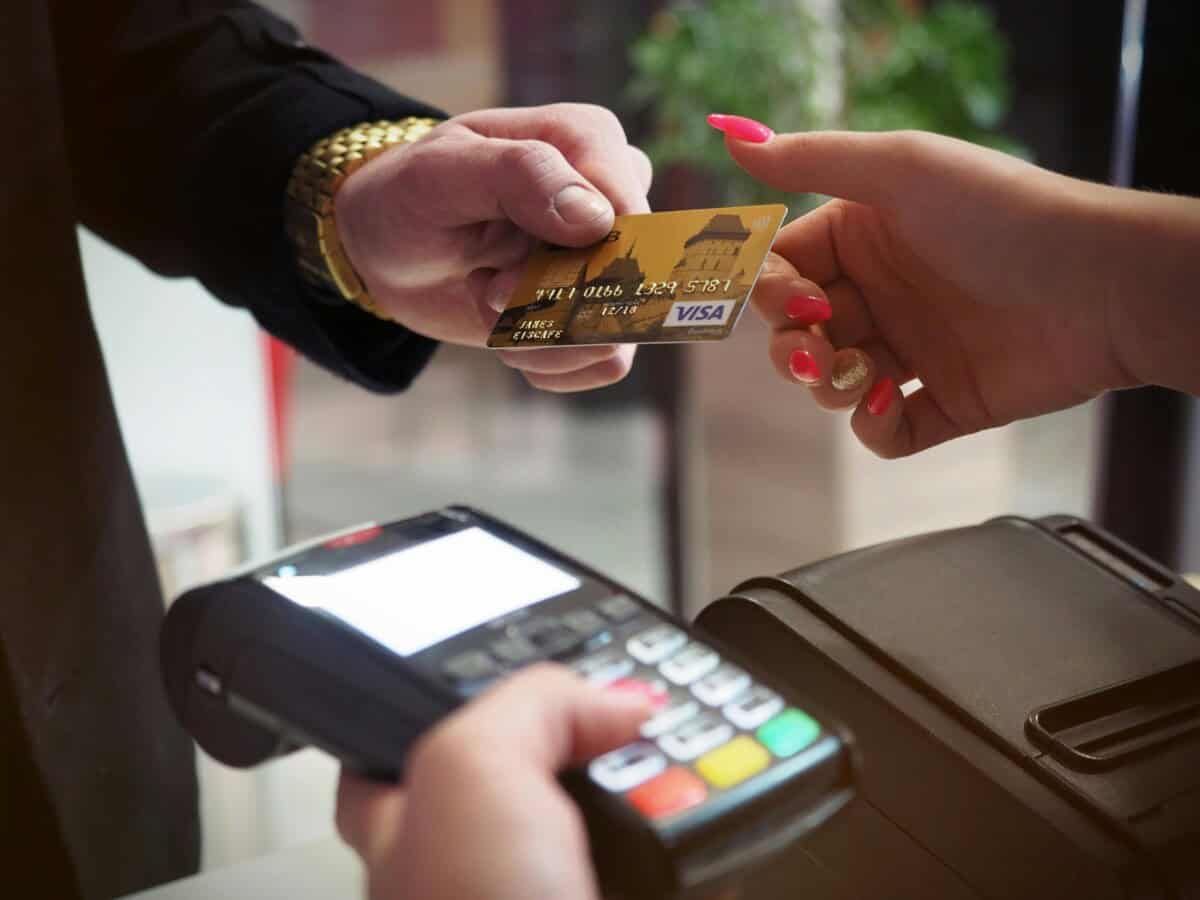
Comparing Important Payment Features for Businesses
Different businesses have different transaction requirements. A small online store may mainly need a simple checkout system, whereas a subscription-based software company may require recurring billing and customer payment management. Understanding these differences helps business owners identify the features that matter most.
| Payment feature | Main purpose | Business benefit |
|---|---|---|
| Online checkout | Accept digital payments | Simplifies customer purchases |
| Recurring billing | Collect scheduled payments | Supports subscription revenue |
| Fraud detection | Identify suspicious transactions | Helps manage payment risks |
| Payment reporting | Monitor transaction activity | Improves financial visibility |
| Payment integrations | Connect business applications | Reduces manual administration |
| International payments | Support eligible cross-border sales | Helps businesses reach global customers |
The table highlights how different payment capabilities contribute to daily business operations. However, not every company needs every feature. Business owners should evaluate their transaction volume, customer locations, technical resources, and financial requirements before selecting a payment setup.
How Businesses Can Benefit from Better Payment Infrastructure
Efficient payment infrastructure can influence several areas of business performance. One major benefit is improved operational organization. When payment processing, billing, and transaction reporting are connected, businesses can spend less time managing repetitive financial tasks. Employees can focus more attention on customer support, product development, marketing, and other activities that contribute to business growth.
Another advantage is the opportunity to improve customer convenience. Customers expect businesses to provide clear pricing, familiar payment options, and understandable checkout processes. A poorly designed payment experience can create confusion and discourage customers from completing their purchases. Companies should therefore focus on making payment journeys straightforward while providing clear confirmation after successful transactions.
Scalability is equally important. A growing company may need to handle more customers, additional payment methods, and higher transaction volumes. Choosing suitable payment infrastructure at an early stage can help reduce the need for major operational changes later. Nevertheless, businesses should regularly review their payment arrangements to ensure that the selected services continue to match their needs.
Supporting International Business Expansion
The ability to serve customers across different countries is an important consideration for companies planning to expand beyond their domestic markets. International customers may prefer different currencies, card networks, and payment experiences. Businesses that want to reach overseas markets need payment infrastructure that can support cross-border transactions while helping them manage currency-related requirements.
Stripe supports international payment capabilities in eligible markets, including multiple currencies and payment methods. This can help businesses create more convenient purchasing experiences for customers in different regions. For example, a digital service provider based in one country may sell subscriptions to customers living in several other countries. Supporting appropriate international payment options can make the purchasing process more accessible.
However, international payment acceptance involves additional considerations, such as currency conversion charges, local financial regulations, supported payment methods, and settlement requirements. Companies should review these factors before entering a new market rather than assuming that every payment option is available everywhere.
Integration with Existing Business Systems
Businesses often use several digital applications to manage their daily activities. These may include accounting software, inventory management platforms, customer relationship management systems, and e-commerce solutions. When payment infrastructure can connect with these applications, companies can create a more organized operational environment.
Payment APIs and ready-made integrations can help developers connect transaction processing with existing websites and applications. For example, an online retailer may connect its payment system with inventory management software so that successful purchases can trigger order-processing activities. Similarly, a service provider may connect billing information with accounting software to simplify financial record management.
The integration approach should depend on the company’s technical resources and business requirements. Smaller organizations may prefer prebuilt checkout solutions because they require less development work, while larger companies may need customized integrations. Selecting an appropriate implementation can help businesses maintain a consistent payment experience without creating unnecessary technical complexity.
Stripe Pricing and Cost Considerations
Payment processing costs are an important part of business planning. Every transaction-based service has pricing conditions that can influence profit margins, particularly for companies handling a large number of payments. Business owners should understand processing fees, currency conversion charges, refund policies, and additional service costs before choosing a payment provider.
Pricing can vary according to the country where the business operates, the type of payment method used, and the nature of the transaction. In India, the published standard pricing includes different rates for domestic and international cards, while currency conversion may involve additional charges. Businesses should check the latest applicable pricing rather than relying on general estimates.
For a company processing hundreds of transactions every month, even small differences in processing costs can influence overall expenses. Comparing pricing structures can help business owners estimate the actual cost of accepting payments and determine whether a particular service fits their budget.
Important factors to review before selecting a payment platform include:
-
Domestic and international transaction processing charges.
-
Currency conversion and settlement-related costs.
-
Refund, dispute, and chargeback procedures.
-
Additional fees for optional services and integrations.
-
Availability of customer support and technical assistance.
A transparent understanding of these expenses can help businesses avoid unexpected costs. Companies should also calculate their average transaction value and monthly payment volume to understand how processing fees may affect their financial performance.
Current Payment Processing Scenario in India
India’s digital payment environment continues to develop as businesses increasingly adopt online commerce, digital services, and cross-border selling models. However, payment service availability is not identical across every provider or country. Companies operating in India must pay attention to local regulatory requirements, supported payment methods, account eligibility, and verification procedures.
An important current consideration is that Stripe services in India are invite-only. Indian businesses generally need to request an invitation rather than creating a new account through the standard online registration process. The platform currently focuses on supporting selected businesses, particularly those interested in international expansion.
Payment method availability also requires careful attention. For eligible Indian accounts, Visa and Mastercard are supported for domestic and international payments, while certain other payment methods have specific restrictions. Local options such as UPI, net banking, buy-now-pay-later, and EMIs are not currently supported for Indian businesses through this service.
Another important development concerns customer verification. Effective January 1, 2026, new Indian users onboarding to the platform are subject to video KYC requirements under the revised RBI payment aggregator guidelines. Businesses invited to apply may need to complete a live video verification session as part of the onboarding process.
These developments demonstrate why business owners should review current service conditions before making implementation decisions. A payment platform that works well for an international company may have different availability and requirements for an Indian business. Understanding these differences can prevent delays and help companies choose an appropriate payment strategy.
Conclusion
Digital payment technology has become an essential part of modern business operations. Companies need convenient ways to accept payments, manage revenue, monitor transactions, and provide customers with reliable purchasing experiences. Choosing suitable payment infrastructure can simplify these activities while helping businesses improve their operational organization and prepare for future growth.
Stripe provides a range of capabilities covering online payment acceptance, recurring billing, fraud prevention, payment reporting, and international transactions in eligible markets. These features can support different business models, from online retail stores to subscription-based platforms and growing digital companies. However, businesses should carefully evaluate pricing, integration requirements, security responsibilities, and regional availability before adopting any payment solution.